
Health insurance in Switzerland — how it actually works.
Swiss health insurance works in two layers. Basic insurance (KVG) is compulsory for every resident, identical at every insurer, and every insurer must accept you — you have three months from registering with your commune to take it out. Supplementary (VVG) is optional and underwritten. Premiums differ by canton — for identical basic benefits.
45 minutes with Robert. Free.
In English · With or
We'll send you a short intake form so we understand your needs before we speak.
Your details
You're booked
Check your email for a calendar invite and a video call link.
Is health insurance mandatory in Switzerland? The three facts that matter first.
Mandatory
Yes — within three months.
Basic health insurance is compulsory for every Swiss resident (Art. 3 KVG), regardless of nationality, age, or health history — and every insurer must accept you. New arrivals have three months from registering with their commune.
Enrolled on time, cover and premiums run from your registration date.
Two layers
Basic is identical. Supplementary isn’t.
Basic (KVG) benefits are fixed by federal law — identical at every insurer, so only price and service differ. Supplementary (VVG) is optional, medically underwritten, and varies contract by contract.
The cost
CHF 440–770 a month — canton decides.
Same benefits, different price. 2027 median for an adult (age 30, Standard model, Franchise 300, with accident): from CHF 444 in Zug to CHF 771 in Geneva. The levers you control — franchise, model, insurer — move it further.


Three situations, three deeper pages.
This page explains the system. The real decisions live one level down — pick the page that matches where you are, and it takes you through the whole sequence. Just arrived? Start with health insurance for foreigners moving to Switzerland.
The whole setup, done right
You usually have three months — and enrolled on time, cover and premiums run from your registration date. The sequence: accident cover, franchise, model, supplementary.
The newcomer setup → Choosing an insurerThere is no best — there is right for you
Basic benefits are identical by federal law, so "best" is really canton × franchise × model × supplementary underwriting. We rank what actually differs.
The insurer comparison → Already insuredTwo deadlines, one calm review
Supplementary usually by 30 September, basic by 30 November. We read both contracts and only move what should move — often the answer is stay.
The switching review →How does health insurance work in Switzerland? Two layers, two federal laws.
The Federal Health Insurance Act (KVG) mandates basic insurance for every Swiss resident and fixes the catalogue of covered care. The Federal Insurance Contract Act (VVG) governs optional supplementary insurance, which insurers underwrite individually. The two layers can sit with the same insurer or different insurers — the law explicitly permits the split, and most readers don't know it.
Basic — KVG
Mandatory. Federal benefits identical.
Required for every Swiss resident under Art. 3 KVG. Catalogue of covered medical care identical at every insurer (Art. 25 KVG): doctor visits, general-ward hospital stays in your canton, listed medications, maternity care. 30+ Swiss basic insurers; you choose freely (Art. 4 KVG) and every one of them must accept you.
- No underwriting — acceptance is mandatory (Art. 5 KVAG)
- Six legal Franchise tiers (Art. 93 KVV); family cap under Art. 64 §4
- Annual cancellation by 30 November (Art. 7 KVG) + extraordinary right (Art. 7 §2)
- Switching never touches benefits — the federal-law guarantee
Supplementary — VVG
Optional. Underwritten individually.
Hospital supplementary (semi-private, private, worldwide), outpatient supplementary (complementary medicine, prevention, glasses, dental), travel and emergency abroad. Each insurer writes its own contract terms, waiting periods, age-based price curves, and exclusion lists — two "semi-private" plans can differ dramatically.
- Health questionnaire on every application (Art. 4 VVG)
- Cancellation per contract — typically 3 months' notice
- The underwriting cliff: conditions developed since signing become potential exclusions on any switch
- Genuinely optional — sometimes our recommendation is to skip it
| Basic (KVG) | Supplementary (VVG) | |
|---|---|---|
| Mandatory? | Yes — every Swiss resident (Art. 3 KVG) | Optional |
| Benefits | Identical across every insurer (Art. 25 KVG) | Vary by insurer and product |
| Underwriting | None — acceptance mandatory | Individual — health questionnaire (Art. 4 VVG) |
| Cancellation | Annual, by 30 November (Art. 7 KVG) | Per contract — typically 3 months' notice |
| Switching consequences | None on benefits | Underwriting cliff — pre-existing conditions may be excluded |
| Where the mechanics live | Switching · Newcomer setup | Hospital Insurance Cost Index |
How much does health insurance cost in Switzerland? Same benefits, different price.
Two adults on the same insurer's same plan with the same Franchise can pay materially different premiums depending on canton — the federal funding split (Art. 49a KVG) and cantonal cost-of-care drive the pattern. Below: verified 2027 median monthly premium for an adult age 30, Standardmodell, Franchise 300 with accident — the FOPH premium data behind our premium calculator. Each linked canton page runs the full breakdown.
| Canton | 2027 monthly · median | vs Swiss median |
|---|---|---|
| Zug | CHF 444 | −26% — lowest in Switzerland |
| Appenzell IR | CHF 466 | −22% |
| Nidwalden / Obwalden / Uri | CHF 513–518 | −13% to −14% |
| Zürich | CHF 677 / 610 / 570 | −4% to +14% — three regions |
| Bern | CHF 700 / 634 / 597 | 0% to +17% — three regions |
| Basel-Stadt | CHF 734 | +23% |
| Vaud (Lausanne) | CHF 721 | +21% |
| Geneva | CHF 771 | +29% — highest in Switzerland |
| Ticino (Lugano) | CHF 764 | +28% |
Median across insurers per canton or premium region · age 30 · Standardmodell · Franchise 300 · with accident · 2027 approved tariffs (FOPH, 29 September 2026). vs Swiss median: against the median Standard offer across Switzerland on the same terms, CHF 596.10. The FOPH's own 2027 canton means were not yet published.
Moderate-earning households can claim IPV (Individual Premium Reduction / Prämienverbilligung) — a cantonal subsidy with materially different thresholds per canton. For most newcomers it becomes relevant in year 2, once Swiss tax residency is established.
How to choose health insurance in Switzerland: what you can actually change.
Choosing Swiss health insurance is less about the brand than about four levers. Federal law fixes the benefits; four levers set your price. Most readers focus on the first when the largest swings come from the fourth — and the cheapest single decision is often the third. The order matters, and the levers interact.
Lever 01
Insurer.
30+ Swiss basic insurers, identical federal benefits (Art. 25 KVG). Competition runs on premium, model availability per canton, claim-handling reputation, and supplementary product range. The largest insurer in your canton is rarely the cheapest — and cheapest-on-paper changes year to year as insurers re-price.
Lever 02
Canton — the lever you pull by living.
Premium varies materially by canton through the federal funding split (Art. 49a KVG): cantons fund at least 55% of inpatient hospital costs, insurers the rest. Geneva runs ≈+25% above the federal average; Zug ≈−33% below. Within cantons, premium regions add another step — the Zürich city line is worth CHF 57/month on identical coverage.
Lever 03
Franchise — the deductible.
Six legal adult tiers under Art. 93 KVV: 300, 500, 1,000, 1,500, 2,000, 2,500 CHF — plus 10% coinsurance above the Franchise, capped at CHF 700/year. Higher Franchise, lower premium. The right tier depends on actual care usage, not optimism — the calculator below runs the federal math for your situation.
Lever 04
Model — the biggest quiet saving.
Standardmodell, Hausarzt, HMO, Telmed, Pharmed. 8–18% premium variance across models within the same insurer — the largest single saving lever for healthy adults, and frequently overlooked because it means committing to a network GP or a telehealth-first protocol. English-language availability varies by canton; verify before signing.
Find your Franchise tier.
Enter your approximate medical spend in a typical year. The calculator runs the federal-rule math — the regulated premium discount per tier, 10% coinsurance, the CHF 700 annual cap — and shows the total annual cost at each Franchise level. Verify against your insurer's published premium for your canton, age, and model before committing.
Interactive · Indicative figures
Find your Franchise tier.
Enter your approximate yearly medical costs, your canton, age tier, and model. The calculator runs the federally-regulated Franchise math (Art. 64 KVG and Art. 93 KVV: six tiers, 10% coinsurance up to CHF 700/year cap) and shows total annual cost for each tier. Lowest tier is highlighted. Premium baselines are the FOPH's 2027 approved premiums (Region 1 medians, every canton) — the data behind our premium calculator. Adults only — Swiss basic insurance has just two adult age tiers under KVG (19–25 and 26+); children have separate Franchise tiers and a family cap, see family Franchise strategy.
| Franchise | Monthly premium | Annual premium | Out-of-pocket | Total annual cost |
|---|---|---|---|---|
| CHF 300 | — | — | — | — |
| CHF 500 | — | — | — | — |
| CHF 1'000 | — | — | — | — |
| CHF 1'500 | — | — | — | — |
| CHF 2'000 | — | — | — | — |
| CHF 2'500 | — | — | — | — |
Choose a value to see the lowest-total Franchise tier for your situation.
The Franchise decision compounds — once a year, every year. We model this against your actual 3-year care history in the 45-minute review.
Supplementary health insurance — when it matters.
Supplementary insurance is optional and individually underwritten (Art. 4 VVG). The pattern we repeat in reviews: take it before you need it, switch it rarely, and skip what doesn't fit your life.
01
Hospital supplementary — semi-private vs private
Semi-private adds a 2-bed room and free choice of doctor within the contracted network; private adds a single room with chief-physician access; worldwide tiers extend cover internationally. The age curve at signup decides the lifetime cost — the entry premium doesn't. Mechanics and current price bands in the Hospital Insurance Cost Index and the semi-private vs private deep-dive.
02
Outpatient supplementary — the everyday layer
Complementary medicine through EMR/ASCA-registered practitioners, prevention contributions (gym, fitness), glasses, travel emergency, limited adult dental. Per-product contract reads in our SWICA review and our Sanitas review.
03
The underwriting cliff — why we say stay over switch
Every supplementary application triggers a fresh health questionnaire (Art. 4 VVG), and answers must be complete — incomplete disclosure can void the contract (Art. 6 VVG). Conditions developed since the original signing become potential exclusions, surcharges, or rejection on any switch. The four possible outcomes sit in our pre-existing-conditions reference.
Where to start — by life stage.
The federal system is the same for everyone; the right architecture depends on where the household is in its life. Pick the row closest to yours.
| Life stage | What matters most | Where to start |
|---|---|---|
| New arrival in Switzerland | The three-month deadline, first-decision architecture | Newcomer setup → |
| Existing resident considering a switch | 30 November deadline, four levers | Switching → |
| Pregnant or planning a baby | Pre-birth registration, supplementary timing | Maternity & newborn → |
| Family with children | Family Franchise cap, model choice, school-age care | Expat family matters → |
| Self-employed | UVG opt-in, KVG accident inclusion, 3a regime | Self-employed 3rd pillar → |
| Executive with international package | KVG-exemption rules, IPMI vs Swiss supplementary | IPMI vs supplementary → |
| Mental health support | What KVG covers under the Anordnungsmodell | Mental health services → |
| Leaving Switzerland | Coverage transition, pension withdrawal | Leaving Switzerland → |
Why an independent advisor, not a comparison portal.
Comparison portals are useful for premium comparison once you have decided canton, age band, Franchise, and model. They are not regulated as insurance intermediaries, and they do not read contracts. The structural difference matters at the moment a claim is contested.
| Comparison portal | Insurer's "review" call | Independent advisor (us) | |
|---|---|---|---|
| Reads your contract | No | Yes — that insurer only | Yes — full document, page by page |
| Runs all four levers | Premium-only | Within their product range | Across the whole market |
| Recommends staying when staying is right | Rarely | Almost never | Often — most reviews |
| Regulated as insurance intermediary | No | Yes — tied | Yes — untied (Art. 45 VAG) |
| Discloses how it's paid | Not required | Yes — to that insurer | Yes — Art. 45 VAG disclosure |
We use priminfo.ch — the federal premium portal — ourselves for cross-canton lookups. The longer answer to what an independent Swiss insurance advisor is sits at our positioning piece.
We read the contracts so you don't have to.
The useful review is not a product list. It is your situation run through the whole system — deadline, layers, levers, supplementary — and then in writing.
-
Your situation, mapped
Canton, household, employment, existing coverage, the year ahead. Robert runs the health setup; Nicole joins if pension, 3rd pillar, or cross-border tax appears.
-
The levers, run
Insurer, canton region, Franchise, model — the four calculations against your actual usage, not a price list's assumptions.
-
The contracts, read
Basic and supplementary, page by page — the age curves, the exclusion lists, the claim-handling record behind the brochure language.
-
Your Private Client Report
Within 3 working days, everything in writing: what to set up, what to keep, what to skip, the reasoning, and the next administrative step. Most reviews end with stay or restructure — not switch.
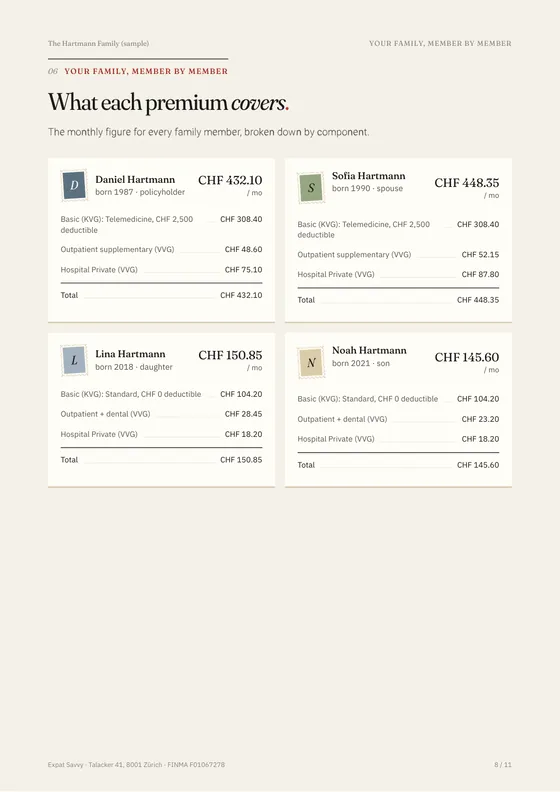
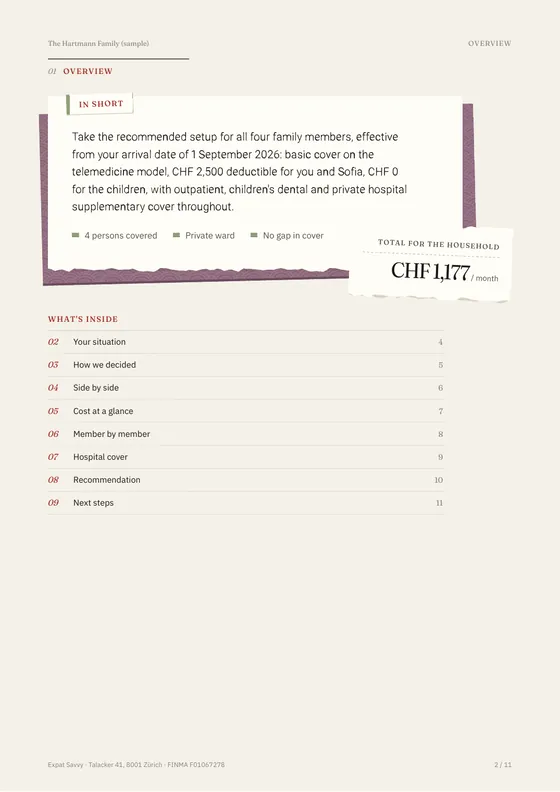
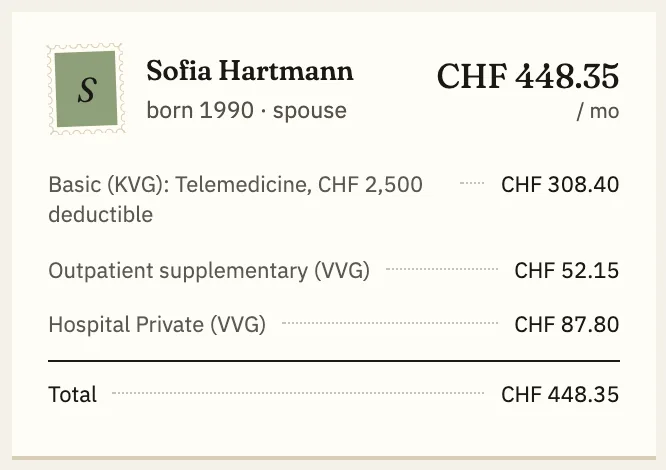
Read the full sample · Download the PDF · What's inside
We measure this market every year.
how much faster premiums grew than consumer prices over the decade
the Zürich city line — region 1 vs region 2, identical coverage
how long a "cheapest" insurer keeps the crown in Zürich, on average
Premiums 2027, canton by canton · Health insurance news and deadlines · The Expat Health Insurance Index (basic) · The Hospital Insurance Cost Index (supplementary)
FAQ.
How does health insurance work in Switzerland?
Do I need health insurance in Switzerland — is it mandatory?
How much does Swiss health insurance cost in 2027?
What is basic health insurance in Switzerland, and how does it differ from supplementary?
How do I choose a Swiss health insurer?
Are basic-insurance benefits the same across all Swiss insurers?
Can I have basic and supplementary insurance with different companies?
Can I cancel and switch Swiss health insurance?
What's the difference between KVG and VVG?
Does Swiss health insurance cover dental?
Does Swiss health insurance cover treatment abroad?
What's the cheapest Swiss health insurance?
What is the Franchise (deductible) and how do I choose it?
Are there subsidies for Swiss health insurance premiums?
What clients say
★★★★★
I was a bit lost with all the administrative procedures after moving to Switzerland, especially regarding my health insurance situation. Nicole took the time to understand my case and explain everything very clearly. She answered all my questions, explained the legal aspects and gave me practical advice on how to move forward. What I appreciated the most is that she was trying to help me solve my problem, not simply sell me an insurance policy.
★★★★★
My session with Robert — without a doubt — was one of the most efficient consultation sessions I'd ever had. He is honest, straightforward and transparent from the outset. He knows the insurance industry inside out. He helped me with my situation without any reservation. You confide to him within minutes into the session and take his honest and unbiased advice.
★★★★★
Robert is the best person to partner with if you need to do difficult things such as relocate and navigate the complications of healthcare insurance in Switzerland. Robert went beyond what was expected and in a very caring way making sure that we had a really good arrival in Switzerland.
★★★★★
Extremely helpful and knowledgeable consultation in all facets of current health insurance offerings. Highly recommend consulting Expat Savvy before making any online insurance comparisons.
See more reviews
★★★★★
I had an excellent experience working with Nicole Bohne. She assisted and guided me through the entire process of obtaining my Swiss pension refund, making what could have been a complicated process incredibly straightforward and stress-free. Nicole was always friendly, professional, knowledgeable, and extremely efficient. She kept me informed every step of the way, answered all my questions promptly, and ensured everything was handled smoothly from start to finish. I highly recommend Nicole and her company to anyone needing assistance with Swiss pension refunds or related services.
★★★★★
I highly recommend this office for all types of insurance. After having several bad experiences with other brokers, working with Mr. Robert Kolar was a completely different experience. He is incredibly professional, friendly, and solved my complex insurance problems in a timely manner. What I appreciated most was that he took all the time needed to make sure I truly understood my policies.
★★★★★
I had an excellent experience working with Robert. I was looking to change providers for one of my supplementary insurance plans, and he guided me through the process with professionalism, patience, and expertise. Thanks to his guidance, I was able to secure a policy that perfectly suits my needs.
★★★★★
After returning to Switzerland from abroad, Robert from Expat Savvy was a tremendous help consulting me about all the changes. He took the time to show me several options and definitely went the extra mile compared to other agents.
★★★★★
Working with Ben was great. Very prompt and responsive. Would highly recommend to anyone!
★★★★★
Benjamin überzeugt durch seine hervorragende Organisation und klare Kommunikation, Robert durch seine kompetente und ehrliche Beratung. Beide arbeiten Hand in Hand und haben die individuellen Anforderungen unserer Kunden immer im Blick — absolut empfehlenswert!
Two layers, four levers. Once you see the structure, the decisions follow.
The 45-minute review is free, in English, with Robert or Nicole. We map the system to your situation — and most reviews end with us recommending stay or restructure rather than switch.
Book your first Swiss insurance review