
The best health insurance in Switzerland is the one that fits you.
"Best" is the most-searched phrase in Swiss health insurance — but the useful answer is by situation. Start with your canton, health history, family plans, and tolerance for claim friction. The insurer name comes after that.
45 minutes with Robert. Free.
In English · With or
We'll send you a short intake form so we understand your needs before we speak.
Your details
You're booked
Check your email for a calendar invite and a video call link.
What is the best health insurance in Switzerland?
Short answer
There is no single best insurer.
Swiss basic health insurance covers the same medical benefits at every insurer. The right setup depends on canton, franchise, model, service tolerance, supplementary underwriting, and how long you expect to stay.
A ranked list is useful only after the situation is clear.
Basic insurance
Compare price, model, and administration.
For basic insurance, the insurer cannot reject you. Price matters, but so do GP/Telmed/HMO access rules, English support, reimbursement behaviour, and whether the model fits your actual doctors.
Supplementary
The contract matters more than the name.
Supplementary insurance is medically underwritten. A plan that looks strong in a table can still be the wrong move if the age curve, exclusions, waiting periods, or claims behaviour do not fit your life.
Where to start instead. New to Switzerland? Start with the setup, not the ranking: setting up health insurance as a new arrival. Already insured? Switching health insurance for 2027. Children? Family health insurance in Switzerland. A hospital ward upgrade? Private hospital insurance. New to the system itself? How health insurance in Switzerland works.
Want names anyway? In the 2026 satisfaction round, Helsana, SWICA, and ÖKK lead a field packed between 4.7 and 5.1 on a 6-point scale — the full table with premiums is below.
The answer changes with your life.
This is the step most search results skip. The same insurer can be sensible for one expat and wrong for another, because the decision is really canton × franchise × model × supplementary underwriting × plans. Pick your situation:
New to Switzerland: the clock is already running.
What matters first: 3-month registration, accident cover, first GP/model choice.
Advisor view: Set up basic first; review supplementary before medical events create underwriting complexity.
The 3-month deadline, explained ·Set it up right the first time
Healthy single or couple: price is your lever — used correctly.
What matters first: Premium, franchise, Telmed/Hausarzt fit.
Advisor view: High franchise can work, but only if cash-flow and usage patterns support it.
Family with children: each member gets their own setup.
What matters first: Child policies, GP access, accident coverage, paediatric extras.
Advisor view: Lowest adult franchise is often not automatically right; child setup differs.
Planning pregnancy: the review comes before the test.
What matters first: Hospital supplementary timing, waiting periods, doctor choice.
Advisor view: Do not wait until pregnancy to review supplementary underwriting.
Existing condition: changing basic is safe — supplementary is not.
What matters first: Supplementary exclusions, claims history, service quality.
Advisor view: Changing basic can be harmless; changing supplementary can be expensive.
Private or semi-private goal: the wording decides, not the label.
What matters first: Contract wording, age curve, hospital lists, chief physician clauses.
Advisor view: The label “private” is not enough; the policy wording decides.
Leaving Switzerland: exit in the right order.
What matters first: Cancellation sequence, international cover, pension/tax overlap.
Advisor view: Robert handles health; Nicole joins if the topic crosses pension, tax, or life insurance.
Use this as a diagnostic map, not a ranking. Robert checks the actual policy before recommending a switch — and if you're weighing one, the two cancellation deadlines decide more than this map does.
Found your situation? That is what the 45 minutes are for — book your first Swiss insurance review.
What you're actually choosing.
Swiss health insurance has two layers: a mandatory basic layer every resident must have, and an optional supplementary layer on top. The "best health insurance in Switzerland" question has a different answer for each layer — and for your specific situation.

Basic health insurance: same coverage, different premiums.
Identical across all insurers
- Doctor visits and specialist referrals
- Hospital stays (general ward, in your canton)
- Prescriptions on the federal list
- Emergency treatment abroad
- Maternity care and childbirth
Varies between insurers
- Monthly premium (by canton, age, region)
- Claim-handling speed
- Service quality and responsiveness
- English-language support
- Digital experience and app quality
The cheapest basic premium today isn't the best basic insurance over ten years. Some low-premium insurers have known patterns of claim friction, late reimbursements, or aggressive case management. We file claims with all of them — we know which behave well.
What's the best deductible for you?
Swiss basic insurance offers six franchise levels for adults: CHF 300, 500, 1,000, 1,500, 2,000, and 2,500. Children have separate tiers from CHF 0 to CHF 600. A higher franchise buys a lower premium — and by law the discount is capped at 70% of the risk you take on (Art. 95 Abs. 2bis KVV), so choosing CHF 2,500 over CHF 300 saves at most CHF 1,540 a year. In Zürich, 21 of 27 insurers charge exactly that cap.
The break-even is not a feeling. In the 2026 Zürich data it sits at about CHF 2'011 of annual medical costs: spend less, the high franchise wins; spend more, the low one does. Slide your expected costs and read your answer — or go deeper in the deductible guide.
The key point: the gap between the lowest and highest franchise is up to CHF 1,540 a year — and the right choice follows your expected usage, not the premium table. For a 34-year-old who sees a doctor twice a year, choosing the lowest franchise costs over CHF 1,000 a year.
Which insurance model fits you?
Standard.
Free doctor choice, no referral needed
Baseline price
Fits: Specialist users, flexibility-seekers
Watch out: Most expensive option — about 11–13% above the other models at the median insurer
Hausarzt.
GP gatekeeper, referrals for specialists
Saves ~CHF 893/yr
Fits: Families, settled residents
Watch out: Requires choosing a GP upfront
Telmed.
Phone/video triage before in-person visit
Saves ~CHF 995/yr
Fits: New arrivals, digital-first
Watch out: Must call hotline before every visit
HMO.
Assigned clinic for all care
Saves ~CHF 1'153/yr
Fits: Cost-conscious, healthy, low-usage
Watch out: Locked to one medical centre
The key point: the model changes how you access care and cuts the premium by about 11–13% at the median insurer (up to 23%) — the franc savings above are 2027 Zürich medians against the same insurer's standard model. For most expats, Hausarzt or Telmed fits better from day one.
Supplementary insurance: where the real differences live.
Basic insurance doesn't cover semi-private or private hospital rooms, adult dental, vision, alternative medicine, maternity extras beyond the federal minimum, or worldwide coverage for non-emergency treatment. This is why supplementary insurance (Zusatzversicherung, governed by the VVG) exists — and why it matters far more than most comparison sites suggest.
The key distinction: supplementary is optional and not regulated the way basic is. Each insurer writes its own contract terms, waiting periods, age-based price curves, and exclusion lists. Two "semi-private" plans from two insurers can differ dramatically in what they actually cover, how they price at age 55, and how they behave when you file a claim.
The more coverage you buy, the bigger the differences between insurers.
This is where the question "best health insurance in Switzerland" stops being academic and starts being personal.
The fine print
Why "private" does not always mean private.
The best private health insurance in Switzerland is decided by the contract wording, not the label on the brochure. We compare the flagships — SWICA Hospita/BestMed, Helsana HOSPITAL Private, Sanitas Hospital Top Liberty — on the dedicated private health insurance page.
Before you switch
Never cancel an existing supplementary policy before the new insurer's written acceptance is in your hands. Underwriting can exclude, surcharge, or decline — and the old door doesn't reopen.
What the label promises — and what the contract says
A supplementary plan labelled "private" promises a private room, treatment by the chief physician, and priority access. What the contract actually says is usually smaller. Common fine-print patterns we see:
- "Private" room if a private bed is available on admission day
- Chief-physician treatment at the clinic's discretion
- Waiting-list systems that route you to semi-private during peak demand
- "Worldwide" plans that exclude elective surgery abroad
- Age-based price escalations that weren't disclosed at signup
Abroad, worked through — what actually pays
Basic insurance (KVG)
Emergencies only, up to twice what the treatment would cost in Switzerland (Art. 36 KVV). Elective treatment abroad: not covered.
Most "worldwide" supplementary plans
Emergencies and some treatment abroad — but elective surgery abroad is often excluded in the fine print. The label doesn't tell you; the policy schedule does.
Worldwide-private flagships
SWICA BestMed (Hospita Private Global): single room, chief physician, worldwide unlimited. Helsana HOSPITAL Private and Sanitas Hospital Top Liberty carry 100% worldwide private built in.
This is the kind of thing we read the contracts for. It's also the single most common reason expats call us three years after signing up. The observed premiums behind every product we compare sit in the full hospital insurance cost index.
Forty-five minutes, then it's in writing.
First-time setup or a review of what you already have — the route is the same. It ends with something you keep, and it doesn't end when the call does.
-
The intake
A short form right after booking — your situation, existing cover, what's ahead. The 45 minutes start prepared.
-
The evaluation
Your life first, policies second. New arrivals get the full setup map; settled clients a read of what they hold. Nothing quoted yet.
-
The consultation
45 minutes in plain English. Insurers compared on how they behave in your case — existing contracts read line by line.
-
Your report
Within 3 working days, everything in writing: what to keep, what to change, what not to buy. Sometimes: keep what you have.
-
Every year after
We observe your policies each autumn and contact you proactively. Reviews are always free — this year and every year.
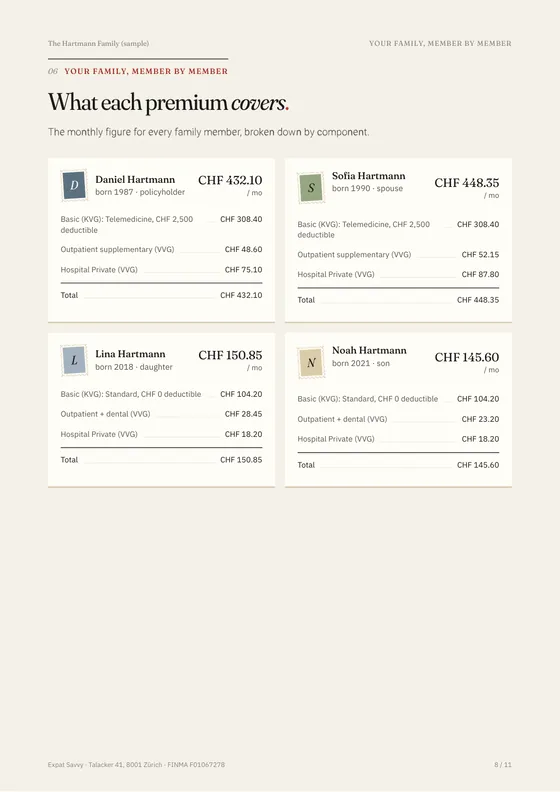
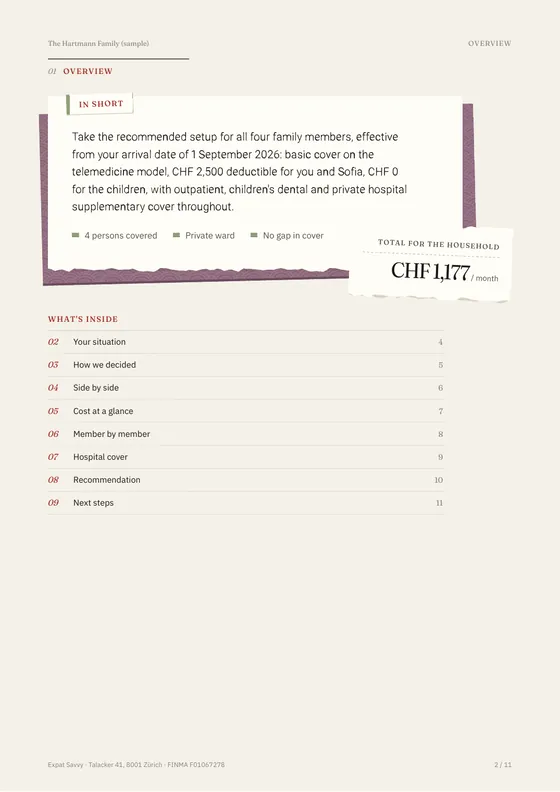
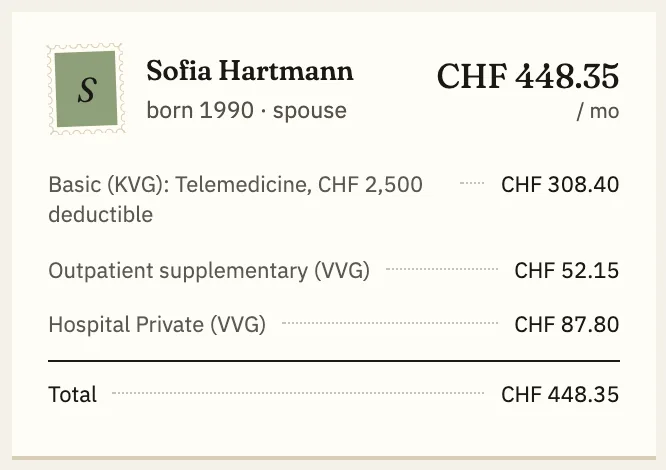
Open it full-screen · Download the PDF · What's inside
What this page cannot decide for you.
This guide can tell you
- How the two layers — KVG basic and VVG supplementary — actually work
- What genuinely differs between the eleven insurers, and what doesn't
- Where the franchise break-even sits, and what each model trades away
- The traps that cost expats the most — age curves, deadlines, fine print
It cannot decide
- Your optimal franchise, against your real usage and cash-flow
- Whether switching insurer is actually worth it in your case
- Whether your health history quietly closes doors you'd want open later
- Whether your doctors fit a Hausarzt or HMO list
- Whether your current policies overlap — or leave a gap
That is what a first review is for. Read the contracts. Spot the traps. Match coverage to your life.
Book your first Swiss insurance review — free, 45 minutes, in English.
Swiss health insurance comparison: what the numbers say.
Every year Comparis and Innofact survey 4,500 residents on satisfaction with their health insurer. In the 2026 round, Helsana, SWICA, and ÖKK lead on overall satisfaction — and the whole field sits in a narrow band, 4.7 to 5.1 on a 6-point scale. Read that narrowness carefully: Switzerland has no bad basic insurer, only bad fits.
Premiums: 2027 basic insurance, Standard model, adult, Zürich city (Region 1), CHF 300 franchise, accident included — the FOPH (BAG) approved premiums, the same data as our premium calculator. Your canton, age, franchise, and model shift these figures — a family-doctor, HMO or telmed model costs less, and so does a higher franchise; compare yours on primai.ch. The binding number for your address sits on priminfo.ch, and our Zürich, Geneva, and Basel pages read the local premium picture in detail. ÖKK, third of the satisfaction leaders, is strongest in Graubünden and eastern Switzerland — outside the eleven insurers we place most expat clients with.
What the scores don't measure
These surveys poll the Swiss mainstream, in German and French. They don't measure what usually decides an expat's experience — English-language service and documents, how underwriting treats newcomers in their clean window, worldwide cover, claims handled in English. An insurer can score 5.1 with Swiss families who've held the same policy for decades and still frustrate a newly-arrived professional — and the reverse. That gap is what the 45-minute review checks.
They don't measure claims behaviour either. Every insurer's brochure looks generous — the real question is which ones actually approve claims quickly, and which ones turn a CHF 3,200 dental crown into a six-month case-manager negotiation. Coverage that pays vs. coverage that fights: we know the difference because we've filed claims with all eleven.
What we see across the insurers.
Scores measure satisfaction, not fit. We've placed clients with all eleven — pick one, and here's what the numbers don't show. Each name below has its own full profile.
Helsana: who it suits, what to watch.
Strengths: Widest supplementary product range, strong hospital network.
Trade-offs: Complex product matrix, age-curve steep on Top plans.
Tends to fit: Clients who want maximum coverage options.
SWICA: who it suits, what to watch.
Strengths: Best preventive care benefits, strong alternative medicine.
Trade-offs: Premium tier pricing, less competitive on basic.
Tends to fit: Health-conscious expats, families with kids.
KPT: who it suits, what to watch.
Strengths: Transparent pricing, good customer satisfaction scores.
Trade-offs: Bern-centric, smaller footprint nationally.
Tends to fit: Bern region, transparency-seekers.
Concordia: who it suits, what to watch.
Strengths: Fair pricing at older ages, strong dental supplementary.
Trade-offs: Smaller brand, fewer digital features.
Tends to fit: Settled families, dental-heavy usage.
Sanitas: who it suits, what to watch.
Strengths: Good international coverage, solid digital tools.
Trade-offs: Smaller provider network in some cantons.
Tends to fit: Globally mobile professionals.
Visana: who it suits, what to watch.
Strengths: Good employer group plans, solid accident cover.
Trade-offs: Less competitive for individual supplementary.
Tends to fit: Employer-group members.
Sympany: who it suits, what to watch.
Strengths: Competitive in Basel/NW Switzerland, simple product range.
Trade-offs: Limited national presence.
Tends to fit: Basel region residents.
CSS: who it suits, what to watch.
Strengths: Strong digital experience, fast claim processing.
Trade-offs: Supplementary premiums above average at 50+.
Tends to fit: Digital-first professionals, families.
Atupri: who it suits, what to watch.
Strengths: Competitive basic premiums, clean digital UX.
Trade-offs: Limited supplementary range.
Tends to fit: Young professionals, basic-only.
Groupe Mutuel: who it suits, what to watch.
Strengths: Multi-brand flexibility, strong in Romandie.
Trade-offs: Inconsistent service across brands.
Tends to fit: French-speaking cantons, bundlers.
Assura: who it suits, what to watch.
Strengths: Among the lowest basic premiums; the cheapest in Geneva.
Trade-offs: Minimal service, slow claim turnaround, French-first.
Tends to fit: Cost-sensitive, healthy, low-usage residents.
For head-to-head reads across the insurers we see most often in consultations:
Some of the people we've advised — and what we recommended.
Yuki · 28 · Sapporo → Zürich, 2024
First job in Switzerland, first time outside Japan. Her employer's HR suggested the same insurer they use for group plans — but individual and group coverage are different products with different terms.
We set her up with a high-franchise basic plan to keep premiums low, and added supplementary while her health declaration was clean. At 28, every insurer accepts you. At 38 with a medical history, some won't.
The best time to apply for supplementary insurance is before you need it.
Amir & Sara · 35 + 33 · Tehran → Zug, 2024
Young family, first child due in four months. Arrived on a C permit with employer-arranged basic insurance. Nobody had mentioned supplementary maternity coverage — or that the waiting period on most plans is 270 days.
We found one insurer with a shorter maternity waiting period for the supplementary tier they needed. The basic plan covered the birth regardless, but the hospital class and obstetrician choice depended on getting this right.
Two hundred and seventy days. That's the number that determines whether you choose your obstetrician or your canton does.
James · 42 · London → Basel, 2023
Senior pharma hire, relocated with family. His employer offered a group insurance option that looked comprehensive on the summary sheet but had gaps in dental, alternative medicine, and cross-border coverage for his wife's French GP.
We kept the employer's basic plan — it was competitive — and layered individual supplementary from a different insurer where the product actually matched their usage.
Employer plans are a starting point, not a finished answer.
Sophie & Thomas · 44 + 46 · Paris → Geneva, 2024
Dual-income couple, both on separate insurers, four products between them, none of which they'd reviewed since arrival six years ago. Their combined supplementary premiums had climbed significantly since signup.
We consolidated to two products each, moved them onto the same insurer for administrative simplicity, and reduced their annual supplementary spend meaningfully — without losing any coverage they actually used.
The most common insurance problem isn't the wrong insurer. It's the right insurer with the wrong products six years later.
Margareta · 61 · Vienna → Lausanne, 2023
Late-career academic, relocating for a three-year university appointment. At 61, supplementary insurance applications trigger longer health declarations and higher premiums. Two of the three insurers she applied to added exclusions.
We found the insurer with the cleanest acceptance at her age and health profile. The premium was higher than she expected — but the alternative was no supplementary coverage at all.
At 61, the question isn't which insurer is cheapest. It's which insurer will still say yes.
Frequently asked.
How do I compare Swiss health insurance providers?
Is the basic plan really identical across insurers?
Which health insurance is best for expats in Switzerland?
What is the 3-month registration deadline, and what happens if I miss it?
Can I switch health insurance mid-year?
Do I need supplementary insurance at all?
How much does supplementary actually cost at age 40, 50, 60?
Is the review really free — and do I have to switch?
What if I leave Switzerland?
What clients say
★★★★★
I was a bit lost with all the administrative procedures after moving to Switzerland, especially regarding my health insurance situation. Nicole took the time to understand my case and explain everything very clearly. She answered all my questions, explained the legal aspects and gave me practical advice on how to move forward. What I appreciated the most is that she was trying to help me solve my problem, not simply sell me an insurance policy.
★★★★★
My session with Robert — without a doubt — was one of the most efficient consultation sessions I'd ever had. He is honest, straightforward and transparent from the outset. He knows the insurance industry inside out. He helped me with my situation without any reservation. You confide to him within minutes into the session and take his honest and unbiased advice.
★★★★★
Robert is the best person to partner with if you need to do difficult things such as relocate and navigate the complications of healthcare insurance in Switzerland. Robert went beyond what was expected and in a very caring way making sure that we had a really good arrival in Switzerland.
★★★★★
Extremely helpful and knowledgeable consultation in all facets of current health insurance offerings. Highly recommend consulting Expat Savvy before making any online insurance comparisons.
See more reviews
★★★★★
I had an excellent experience working with Nicole Bohne. She assisted and guided me through the entire process of obtaining my Swiss pension refund, making what could have been a complicated process incredibly straightforward and stress-free. Nicole was always friendly, professional, knowledgeable, and extremely efficient. She kept me informed every step of the way, answered all my questions promptly, and ensured everything was handled smoothly from start to finish. I highly recommend Nicole and her company to anyone needing assistance with Swiss pension refunds or related services.
★★★★★
I highly recommend this office for all types of insurance. After having several bad experiences with other brokers, working with Mr. Robert Kolar was a completely different experience. He is incredibly professional, friendly, and solved my complex insurance problems in a timely manner. What I appreciated most was that he took all the time needed to make sure I truly understood my policies.
★★★★★
I had an excellent experience working with Robert. I was looking to change providers for one of my supplementary insurance plans, and he guided me through the process with professionalism, patience, and expertise. Thanks to his guidance, I was able to secure a policy that perfectly suits my needs.
★★★★★
After returning to Switzerland from abroad, Robert from Expat Savvy was a tremendous help consulting me about all the changes. He took the time to show me several options and definitely went the extra mile compared to other agents.
★★★★★
Working with Ben was great. Very prompt and responsive. Would highly recommend to anyone!
★★★★★
Benjamin überzeugt durch seine hervorragende Organisation und klare Kommunikation, Robert durch seine kompetente und ehrliche Beratung. Beide arbeiten Hand in Hand und haben die individuellen Anforderungen unserer Kunden immer im Blick — absolut empfehlenswert!
Want us to look at your specific situation?
Forty-five minutes. By video or in our Zürich office. Free.
Book your first Swiss insurance reviewYour Private Client Report
Your insurance, reviewed.
Free · 45 minutes · In English
Step 1 of 3: What do you need help with?
Choose one to continue — or Everything if you’re not sure.
A quick question instead? WhatsApp us · +41 79 155 25 70
Step 2 of 3: Pick a day with your advisor.
Monday to Friday, by video, phone or in Zürich.
Times for
Step 3 of 3: Your details.
You’re booked.
Check your email for the calendar invite. Within 3 working days of your review, you receive your report — everything in writing.