
Robert Kolar — health insurance specialist.
Robert is the health-insurance side of Expat Savvy. Over twenty years of experience in Swiss insurance. Basic, supplementary, hospital supplementary, accident insurance — the questions he runs in 45-minute consultations. He says "stay with what you have" more often than he recommends a switch.
- Based in
- Zürich, CH
- In the trade
- 20+ years
- Specialty
- Health insurance
- FINMA
- F01067278
Robert also advises internationally mobile clients — Robert’s profile at expatsavvy.com.
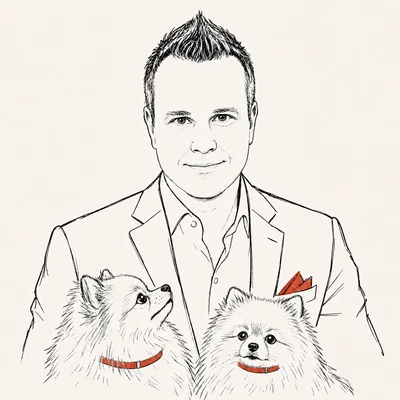
Twenty years in the trade.
Robert is the insurance advisor and health insurance specialist at Expat Savvy, with 20+ years in Swiss insurance. The work is contract-reading, lever calculation, and the four-trap diagnostic — applied to households whose questions span basic insurance, supplementary outpatient and hospital, accident insurance, and the cluster of decisions that compound over decades.
More than fifteen of those years have gone into health insurance specifically — for internationals and for Swiss households alike. Robert is also partner and managing director of Lang + Partner Finanzdienstleistungen GmbH, where he advises private and corporate clients; the firm’s own site, langpartner.ch, runs in German, English and Czech. How Lang + Partner and Expat Savvy fit together is set out on our about page.
The discipline of the work is reading the full contract — standard policy, supplementary conditions, exclusions, claim procedures, definitional clauses — before recommending. The brochure language and the claim-handling reality are different documents. Robert reads both.
He has also been the newcomer working out somebody else’s health system from the outside. It shows in how his reviews run: less like a sales call, more like a translation — what the Swiss rule is, what it means for your household, and what, if anything, to do about it.
We do not recommend insurers based on brochure language. We recommend based on what the contract says when the claim arrives. — Robert Kolar
Independent by law, not by claim.
Robert is entered personally in FINMA’s public register of insurance intermediaries: register number F01104300, a non-tied insurance intermediary since 13 July 2016, for supplementary health, life, non-life, motor and reinsurance business.
“Non-tied” is the register’s word for independent: he is bound to no insurer. His entry names one employer, Lang + Partner Finanzdienstleistungen GmbH — itself registered as a non-tied intermediary since June 2015, under F01067278, the number at the top of this page. Both entries take a minute to check, and we would rather you checked.
What Robert works on.
Four families of question, run in 45-minute consultations. Each gets the same diagnostic: contract on screen, lever maths, four traps mapped to the household, written summary inside three working days.
01 · KVG basic
Basic & cancellation
Insurer + Franchise + model decisions, the November 30 deadline mechanics, new-arrival 3-month registration.
02 · Supplementary
VVG outpatient
Hospital, dental, complementary medicine, age-curve and underwriting cliff. Contract-read on screen.
03 · Hospital tier
Semi-private & private
SWICA Hospita, Helsana HOSPITAL, Sanitas Hospital Liberty — entry-age vs age-banded, network mapping.
04 · Accident
UVG & UVG-Zusatz
BU + NBU status check, the 31-day Nachdeckung rule, salary-ceiling gap, voluntary self-employed affiliation.
The traps he looks for first.
Our four traps, as they turn up on Robert’s desk. None is exotic; each is easy to miss when the brochure is the only document on the table.
- The 3-month deadline. New residents have three months from arrival to take out basic insurance, and cover taken out in time is backdated to the day they arrived. Miss it and the canton assigns an insurer, and a surcharge for late joining can follow. Most people who book Robert are in the middle of a move, so this is the first date he checks.
- The age-curve trap. Supplementary premiums priced by age band look cheap at 32 and are brutal at 55; contracts priced at entry age hold steadier. And because supplementary cover is underwritten, the time to buy it is while the health questions are easy to answer — so Robert raises it early, even when a client came only for basic.
- Coverage that pays vs. coverage that fights. Basic insurance pays for a general-ward stay. Outside your canton it pays only up to your home canton’s tariff, and abroad it covers emergencies, not planned treatment. Everything beyond that is supplementary territory, where the conditions decide whether a claim is paid — which is why he reads them on screen with you.
- We match coverage to your life. He says “stay with what you have” more often than he recommends a switch, and he will tell a newcomer in a shared flat that household contents cover can wait. Fewer products than expected is a normal outcome of his reviews.
What people actually ask him.
Our client files have run in one system since spring 2025, so what crosses Robert’s desk can be counted rather than guessed. The figures run to September 2026.
Of the 118 files with a Swiss address, 68 are in the canton of Zürich and 23 in Zug; Basel, Bern, Aargau, Geneva and a handful of other cantons share the rest. The country named most often in his files is Germany, followed by the United States, the United Kingdom, France and Italy. Almost everyone — 159 of the 162 whose language is recorded — chose to be advised in English.
Before a review, clients can fill in a short questionnaire; 119 did. Fifty-three were insuring only themselves, 33 a couple, and 33 a family of three or more. Twenty-six were not working at the time, which matters: without an employer’s accident insurance, accident cover has to sit inside the health policy. Asked about hospital cover, 51 were content with the general ward and 67 wanted more. Fifty-four had no fixed view on the deductible — the most useful gap to close in 45 minutes — and only 14 said their employer contributes to the premium.
The questions, as they arrive:
- Do I have to be insured from the day I arrived — and what happens if I am late?
- Which deductible? The break-even between CHF 300 and CHF 2,500 sits at roughly CHF 1,800 of medical costs a year; below it, the high deductible wins.
- Will supplementary cover accept me with my medical history?
- Does my employer’s plan cover my partner and children?
- Does my hospital cover work outside my canton, or abroad?
- Do I need household insurance, or only liability?
Three situations, anonymised.
Real reviews from 2026, stripped of anything that could identify the people in them — no names, no employers, no dates. What Robert found, and what changed.
2026 · A premium question
The saving that wasn’t there
A resident of Basel hoped to cut a basic premium roughly in half after seeing advertised savings. Robert priced the same deductible and model with the cheapest insurer for the postcode. The most a switch could save was about CHF 34 a month — around CHF 400 a year. He said so plainly and left the decision with the client.
2026 · Arriving from Singapore
The ward, chosen on the day
A family relocating from Singapore wanted access to their preferred doctors and private hospitals. Robert first set out what basic insurance pays — a general-ward bed, and little beyond the canton — then matched a flexible hospital supplement: the ward is chosen at admission, with a co-payment for the upgrade. The highest deductible for the adults, whose likely costs sat below the break-even; none for the children.
2026 · New in Switzerland
Liability yes, contents no
Three months after arriving, and living in a shared flat, a client asked about liability and household insurance. Robert confirmed that personal liability — around CHF 120 to 150 a year — covered what worried them most: damage to the rented room and to other people’s property. With few belongings in a shared room, he advised against household contents cover for now.
In clients’ own words.
Two excerpts from Google reviews of our Zürich practice that name Robert, quoted exactly. The full reviews are on our Google profile.
He is honest, straightforward and transparent from the outset. — Milad F., Google review, 2025
… he took all the time needed to make sure I truly understood my policies. — Dragos H., Google review, 2026
Recent writing.
Three of Robert's most recent pieces. The full archive sits at the blog.
Three working languages.
Robert works in German and English at full pitch, plus Czech as a working language for Czech, Slovak, and broader Central European clients.
Get in touch.
A first review with Robert is free, in English (or German or Czech), by video call. Bring your policy schedules, the canton, any planned transitions. The mechanics of the call sit at what happens in your first review.
Want a contract-read on your Swiss health insurance?
Forty-five minutes, free, in English. We read the contract on screen, run the lever maths, and tell you whether to stay, switch, or restructure.
Book your first Swiss insurance review