
Robert Kolar
Health insurance
Over twenty years of experience reviewing Swiss basic and supplementary plans. Speaks German, English and Czech. Has personally navigated the Swiss system from the outside in.
Book with RobertNew to Switzerland or reviewing your coverage? We read the Swiss insurance contracts so you don't have to. We spot the traps sales agents won't mention. We match you with what you actually need — not what someone's trying to sell.
Free · 45 minutes · In English · With Robert or Nicole
Not ready to book? Calculate your premium first


45 minutes with Robert. Free.
In English · With or
We'll send you a short intake form so we understand your needs before we speak.
Your details
Check your email for a calendar invite and a video call link.
Where do you stand?
Choose what you want to do.
Basic health insurance comes first: you have three months from registering with your commune to take it out. Then household and liability — often the first thing a landlord asks to see.
In your 45-minute review
Book your first Swiss insurance review
Free · 45 minutes · In English · With Robert
Premiums re-price every autumn. Basic insurance can be switched until 30 November for 1 January; supplementary contracts often have to be cancelled by 30 September. Often the verdict is to change nothing.
In your 45-minute review
Book your first Swiss insurance review
Free · 45 minutes · In English · With Robert
Your pension fund certificate first, then the 3rd pillar. What you pay into pillar 3a comes off your taxable income each year — and whether a bank or an insurance 3a fits depends on how long you plan to stay.
In your 45-minute review
Book your first Swiss insurance review
Free · 45 minutes · In English · With Nicole
A family, a mortgage, income worth protecting. The statutory schemes replace less than most people assume — the review sizes the real gap and puts each franc where it works.
In your 45-minute review
Book your first Swiss insurance review
Free · 45 minutes · In English · With Nicole
What a review covers
A life in Switzerland rests on five layers of cover — from the flat you rent to the pension you will draw. One advisor reads all five in one review.
Household insurance (Hausrat) replaces what you own if it burns, floods or is stolen; personal liability (Privathaftpflicht) pays for damage you cause to others.
Basic health insurance (KVG) is mandatory for everyone who lives here and identical at every insurer by law — so the model, the deductible and your premium region decide what you pay.
Supplementary insurance (VVG) adds a semi-private or private room, your choice of doctor, dental and treatment abroad — where contracts genuinely differ, and all of it underwritten.
Replaces income while illness keeps you from working, and protects a partner, children or a mortgage where IV and your pension fund fall short.
Your own savings on top of AHV and your pension fund — what you pay into pillar 3a comes off your taxable income each year.
All your policies in one overview. Each autumn we read them again against the new premiums and your life, and contact you when something should change. Reviews are always free — this year and every year.
Five layers, one review — and only the cover your life needs.
How a review works
First-time setup or a review of what you already have — the route is the same. It ends with something you keep, and it doesn't end when the call does.
A short form right after booking — your situation, existing cover, what's ahead. The 45 minutes start prepared.
Your life first, policies second. New arrivals get the full setup map; settled clients a read of what they hold. Nothing quoted yet.
45 minutes in plain English. Insurers compared on how they behave in your case — existing contracts read line by line.
Within 3 working days, everything in writing: what to keep, what to change, what not to buy. Sometimes: keep what you have.
Stop 4, in your hands
The Hartmann family is a sample; the structure, depth and reasoning are exactly what a client receives — nine chapters on eleven pages, as a web page and a PDF.
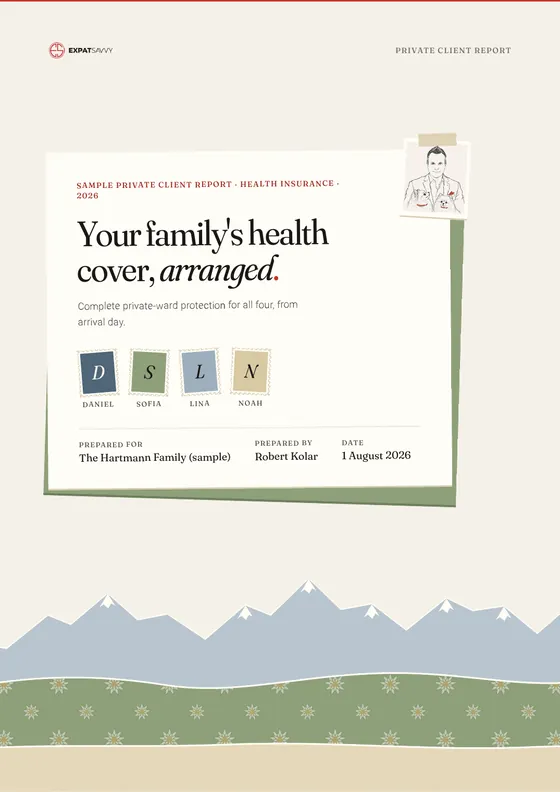
Prepared for you by name, by the advisor who ran your review.
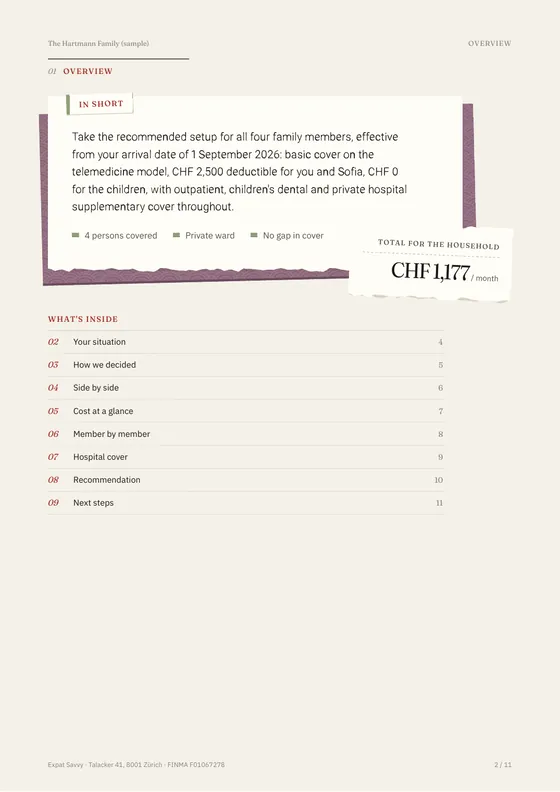
The answer on page two: what to set up, and the total per month.
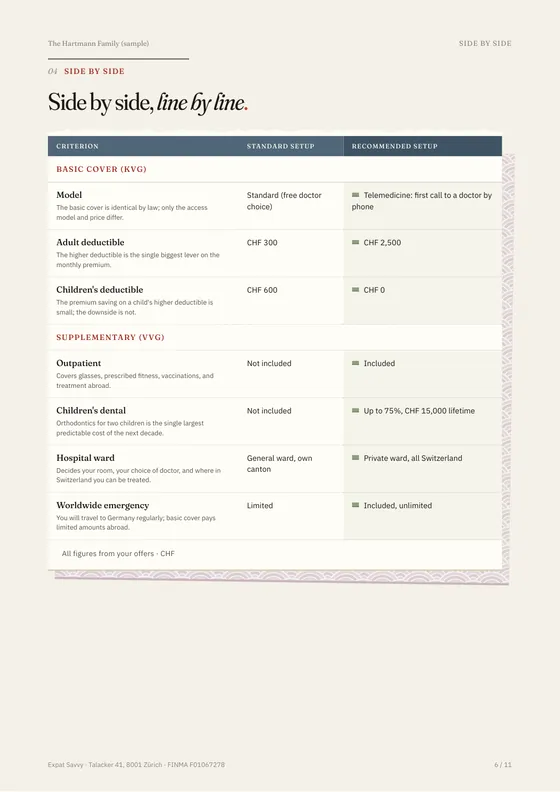
The set-up we recommend beside the one we don’t — with the reason on every line.
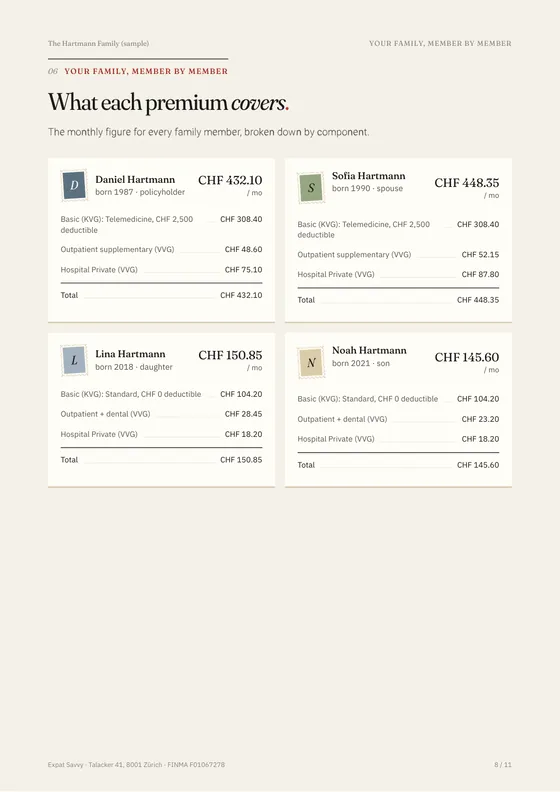
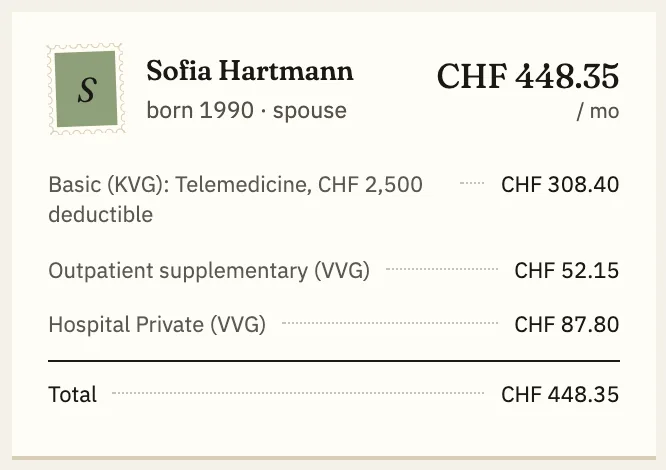
Every family member’s premium, broken down to the centime.
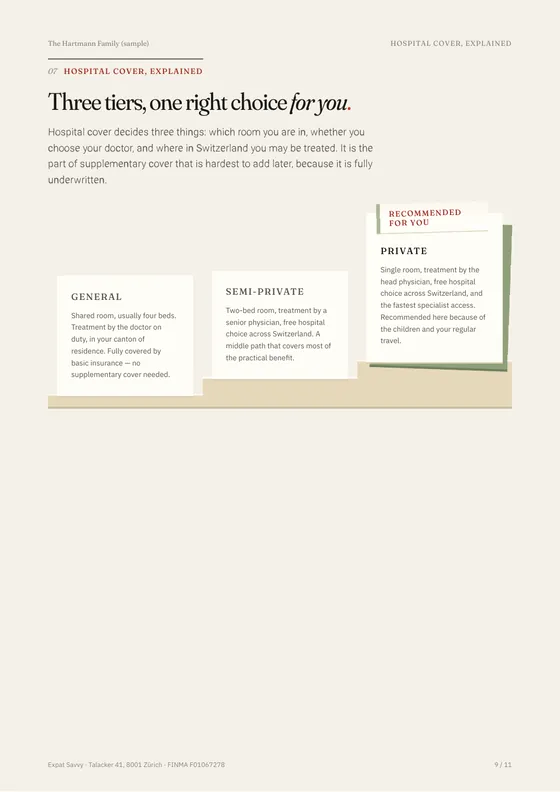
Hospital cover explained tier by tier — and which one fits you.
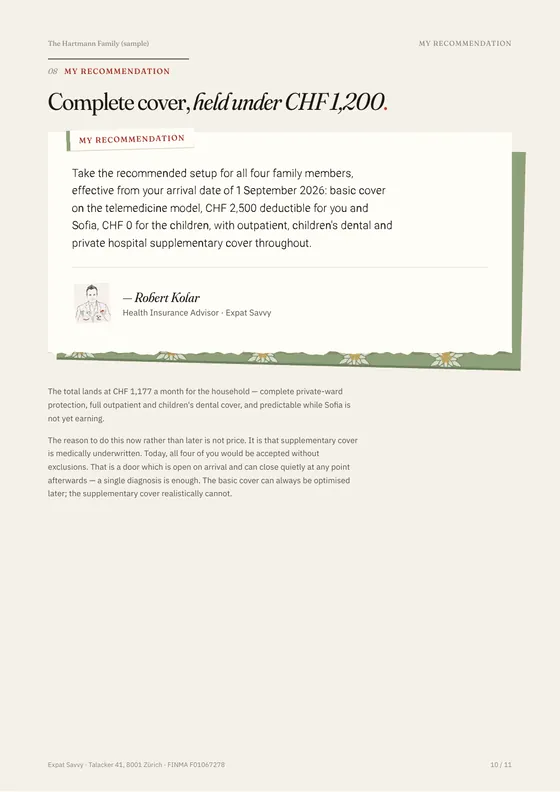
Signed by your advisor, with the reasoning — not just the verdict.
Nine chapters, and what you learn in each
We observe your policies each autumn and contact you proactively. Reviews are always free — this year and every year. The homework, public.
Independent by law, not by claim. A FINMA-registered non-tied intermediary, F01067278 — no exclusive arrangement with any insurer, paid a regulated courtage disclosed under Art. 45 VAG and verifiable on the FINMA public register.
The team
Specialists by topic. Robert handles health insurance; Nicole handles life insurance, 3rd pillar, and tax optimization; and three colleagues cover international health insurance for the years before Switzerland and after it.
Health insurance
Over twenty years of experience reviewing Swiss basic and supplementary plans. Speaks German, English and Czech. Has personally navigated the Swiss system from the outside in.
Book with Robert
Life · 3rd pillar · Tax
Former Basler Versicherung and Zurich Insurance specialist. FINMA F01536402. Nicole reads life-insurance and insurance-wrapped 3a decisions against the household, the BVG, and the tax effect.
Book with Nicole
International health insurance
Came to insurance from luxury and consulting, where the clients were demanding and the work was international. Then a Swiss insurer's international desk — cross-border employees, expats and retirees abroad. Legal training and a master's from Paris Dauphine. English and French.

International health insurance
FINMA-certified independent insurance intermediary, who began in financial advice at Swiss Life. He works with globally mobile households, and coordinates with the insurer when a medical need actually arises — which is where a policy is finally tested. German, French and English.

International health insurance
Client advice for internationally mobile households. English and French. Her fuller biography follows shortly — until it does, this card carries only what we can stand behind.
From the advisory desk
Three composite cases, drawn to the pattern we see every week. The people are illustrative — every number is taken from our published indices and premium bands.

London → Geneva, 2025 · via her relocation agency
Her relocation agency sent one link; she booked the assessment online before her boxes arrived. The advice surprised her: take the private tier — now. At her age our index prices it around CHF 144 a month; the same cover costs a 65-year-old CHF 441, and supplementary is underwritten, so the best terms of her life were on the table exactly once. One more line came out of HR’s default plan on the way: accident cover she already carried by law through her employer, as anyone working at least eight hours a week for one employer does.
"I expected to be talked into the minimum. They told me to take the best — and showed me why it was the cheap decision.

Seattle → Zürich, 2024 · big tech · found us online
Relocated with their daughter, and did it the American way: assume the employer handles the insurance. In Switzerland it doesn’t — health cover is personal, and the three-month clock was already running for all three of them. Basic and supplementary were set up in a week. Then Ananya asked Nicole to read the pension certificate too — and there it was, in one line: if his income stopped, the fund would replace barely a third of the salary they actually live on. Term cover at roughly CHF 35 a month, inside our published band, closed the biggest part of the gap.
"Back home the company handles this. Here, nobody tells you that you are the company.

Brussels → Basel, 2019 · recommended by a colleague
She came with a cheaper offer in hand — and an old contract she was undervaluing: semi-private on an entry-age tariff, still priced at the age she signed, years ago. The new policy was cheaper today because it was attained-age: it rides the curve our index draws, where the same two-bed cover runs CHF 170 a month at 53 and CHF 267 at 65. Hers doesn’t ride it. We put the two lines side by side and she stayed — and found benefits she had paid years for without using: her gym, partly covered all along.
"The cheaper policy was cheaper for a few more years — nobody selling it had mentioned that.
What clients say.
4.8 from 60 reviews on GoogleShe assisted and guided me through the entire process of obtaining my Swiss pension refund.

What I appreciated the most is that she was trying to help me solve my problem, not simply sell me an insurance policy.


After several bad experiences with other brokers, working with Mr. Robert Kolar was a completely different experience.

Robert is the best person to partner with if you need to do difficult things such as relocate.
My session with Robert was one of the most efficient consultation sessions I'd ever had.

I was looking to change a supplementary insurance plan, and Robert guided me with professionalism and patience.


After returning to Switzerland from abroad, Robert was a tremendous help consulting me about all the changes.

Highly recommend consulting Expat Savvy before making any online insurance comparisons.
Working with Ben was great. Very prompt and responsive. Would highly recommend to anyone.


Common questions
Yes. Swiss law requires every resident to hold basic health insurance (KVG) within three months of registering with your commune — whatever your nationality and whatever cover you held abroad. The basic benefits are identical at every insurer; what changes is the price, the service quality, and the supplementary options you can add on top.
Yes — every consultation with Expat Savvy is free, not just the first one. 45 minutes, in English, with no obligation. Advice is paid on a courtage basis: the insurer pays a percentage of the premium when a policy is placed, disclosed under Article 45 VAG. There's no fee for your review, your Private Client Report, or any follow-up conversation.
Cover starts only on the day you join, and your insurer adds a premium surcharge — 30–50% for twice the length of the delay, up to as much as the premiums for the months you weren't covered (Art. 5 KVG, Art. 8 KVV). If you don't join at all, the canton assigns you an insurer. The clock starts on your registration date, not your move-in date, so it's easy to lose track. If you're close to the deadline, talk to us before it passes.
Every Expat Savvy advisor is FINMA-registered (the Swiss financial regulator — our registration is F01067278, verifiable on the public register), and the team holds Certified Financial Planner (IAF) and Swiss federal insurance qualifications. That means supervised, independent advice — legally required to serve your interest, not tied to any single insurer.
Yes. Most expat situations connect — your health cover, your 3rd pillar (3a / 3b) and your tax position all interact. In one 45-minute review we look at all three together, so you're not stitching advice together from three separate places.
Partially — and the illness case is the weak spot. Accidents are covered through your employer under UVG, but for illness the statutory layers (IV pension plus your pension fund's minimum) typically replace only a fraction of a higher salary. Your Pensionskasse certificate states your actual figures; the review reads it, sizes the real gap on the official tables, and — where cover is worth it — checks your case with insurers before you apply.
A first review is free, 45 minutes, in English, with Robert or Nicole. We'll listen first. We'll tell you what we'd do in your situation. You decide what happens next.
Book your first Swiss insurance reviewOr send us a WhatsApp at +41 79 155 25 70 — we reply within the working day.
Expat Savvy at a glance
One advisor reviews your whole situation — basic and supplementary health insurance, household and liability, life and disability protection, and 3rd-pillar pension decisions. The review ends in a written Private Client Report, and sometimes its recommendation is to buy nothing.