
Health insurance premium calculator — compare every insurer by postcode.
This calculator is priminfo in English: it compares every insurer's officially approved 2027 basic premium for your postcode, age, deductible and model, with the change since 2026 and each insurer's history since 2016. Basic benefits are identical, so the ranking is a pure price ranking. To switch for 1 January, switch before 30 November.
2027 premiums are out: the Federal Office of Public Health published them on 29 September 2026. Every insurer below shows your own 2026 → 2027 change. To switch for 1 January, your cancellation must reach your insurer by 30 November. What changed in 2027
Median insurer · 2027
515.20CHF a month
Pick your insurer to see your own premium and its change since 2026.
Cheapest for this profile
471.10CHF a month
Sumiswalder
Cheapest vs most expensive
1'327CHF a year
for identical basic cover — benefits are the same by law
Every insurer, ranked · 2027
monthly premium · change since 2026
- 1 SumiswalderBASE 471.10 +5.1%
- 2 SLKKBASE 474.40 +5.8%
- 3 SanitasBASE 479.90 +4.9%
- 4 EGKBASE 488.40 +4.6%
- 5 WädenswilBASE 489.70 +5.0%
- 6 SympanyBASE 489.90 +6.9%
- 7 AtupriBASE 490.20 +4.2%
- 8 AssuraBASE 491.00 +5.3%
- 9 ConcordiaBASE 495.00 +3.1%
- 10 Mutuel (Groupe Mutuel)BASE 496.30 +4.3%
- 11 KPTBASE 498.10 +3.1%
- 12 ÖKKBASE 505.70 +9.5%
- 13 HelsanaBASE 509.40 +6.4%
- 14 Avenir (Groupe Mutuel)BASE 515.20 +9.2%
- 15 rhenusanaBASE 515.90 +9.0%
- 16 AquilanaBASE 516.60 +5.0%
- 17 Luzerner HinterlandBASE 516.80 +14.0%
- 18 SWICABASE 524.40 +7.4%
- 19 AgrisanoBASE 525.40 +8.1%
- 20 SteffisburgBASE 529.50 +2.5%
- 21 Einsiedler KrankenkasseBASE 534.20 +2.5%
- 22 sana24BASE 536.00 +3.2%
- 23 Philos (Groupe Mutuel)BASE 540.80 +2.7%
- 24 CSSBASE 548.40 +12.8%
- 25 vita surselvaBASE 551.80 +2.8%
- 26 VisanaBASE 566.00 +4.4%
- 27 GalenosBASE 581.70 +4.5%
Zürich city (premium region 1), adult 26+, CHF 2’500 deductible, standard model, accident excluded. Each insurer's cheapest approved tariff for this profile.
The decade behind the price
your insurer market median cheapest that year
History at the CHF 2’500 deductible, so every year compares like with like.
Video · 2:48 How much is health insurance in Switzerland? 2027 by canton
Video page, chapters and transcript
Chapters
- 0:00Why "the average" misleads
- 0:19Canton
- 0:41Deductible
- 1:11Model
- 1:39Supplementary on top
- 2:01Work out your own number
- 2:29Your first Swiss insurance review
Read the transcript
0:00 Why "the average" misleads
How much is health insurance in Switzerland? For 2027, the federal average for an adult is CHF 487.60 a month. But that average blends every deductible and model. What you pay depends on canton, deductible and model.
0:19 Canton
First, your canton. For an adult, the federal average runs from CHF 324.90 a month in Zug to CHF 610.60 in Geneva, for identical benefits. Within a canton, the city usually costs most: in Zürich, about CHF 90 a month more than in Wetzikon.
0:41 Deductible
Second, your deductible. In Zürich city, choosing CHF 2,500 instead of 300 saves CHF 1,527 a year at the middle insurer, if you rarely see a doctor. One procedure of CHF 4,000, though, and you pay CHF 1,980 more out of pocket. Add the premium you saved, and that year costs CHF 453 more.
1:11 Model
Third, your model. Family doctor, HMO or Telmed: a different first contact, the same cover by law. In Zürich city, changing model at the same insurer saves CHF 98.20 to CHF 147.20 a month. Moving to the cheapest insurer on Standard saves CHF 45.05. Model first, insurer second.
1:39 Supplementary on top
Supplementary insurance comes on top, and it is the trap we see most often. Many expats buy one or two tiers more than they use in their first year, and never review it. Right-sizing it typically saves CHF 50 to 200 per adult a month. But never cancel before a new insurer has accepted you.
2:01 Work out your own number
To work out your own number, use our premium calculator, priminfo in English: enter your postcode, age, deductible and model, and every insurer is ranked for you. Employed 8 hours a week or more? Your employer already covers accidents, so leave accident cover out. And to switch on 1 January, your notice must arrive by 30 November.
2:29 Your first Swiss insurance review
If you'd like someone to read your own contracts with you, book your first Swiss insurance review. It's free, 45 minutes, in English, with Robert or Nicole. The link is in the description.
The price is the easy part. Four things it cannot see.
Your supplementary contract
Basic cover moves freely — every insurer must accept you. Supplementary doesn't: a new insurer can ask health questions and say no. Cancel it first and it may be gone for good.
Whether the model fits your life
The cheapest rows are often HMO or telmed. They work well — until you see a specialist without the referral and the claim comes back refused.
Your deductible break-even
CHF 2’500 saves premium. With regular treatment it can cost you more than it saves. The break-even is arithmetic, and it depends on your year, not an average one.
Coverage that pays vs coverage that fights
Premiums are public; claim behaviour isn't. Two insurers at the same price can treat the same invoice very differently. That part we see every week.
Bring your premium letter. Leave with it in writing.
In 45 minutes we read your 2027 premium letter against your supplementary contract, your model and your deductible — then send your free personal report within 3 working days. Sometimes it says keep what you have.
- 01Your situation
- Canton, family, work, the cover you hold today.
- 02How we decided
- The reasoning in writing — why each option won or lost.
- 03Side by side
- The real alternatives, including the one we advised against.
- 04Cost at a glance
- What every person pays, to the franc.
- 05Recommendation
- What to do, in order — and what not to buy.
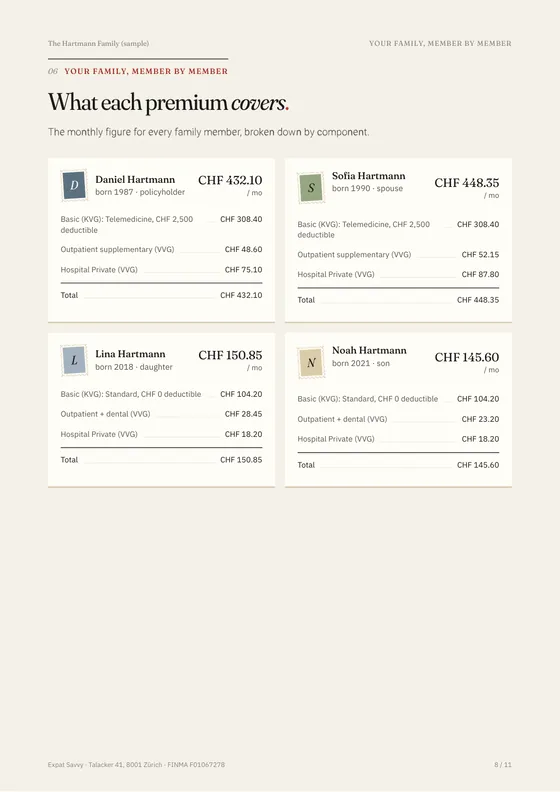
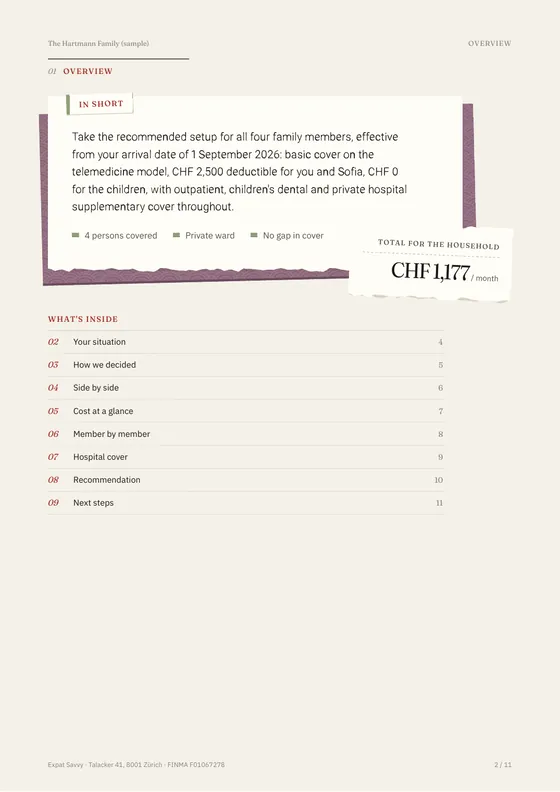
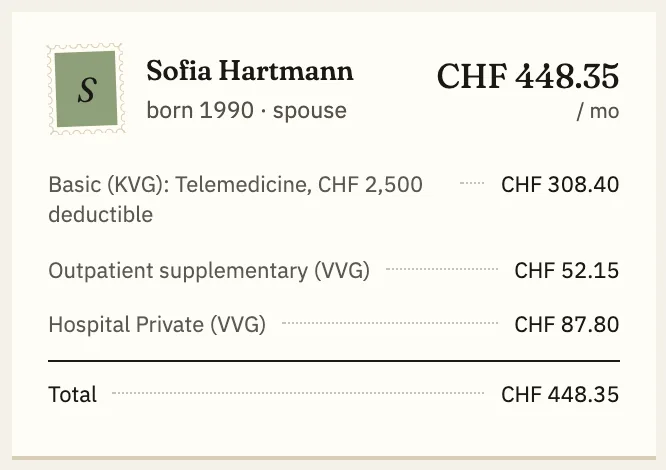
Open it full-screen · Download the PDF · What's inside
Method and source
Every figure is an officially approved list premium from the Federal Office of Public Health's open dataset "Krankenversicherungsprämien", tariff years 2016–2027. For each insurer we show its cheapest approved tariff for the model you pick, in your premium region, age group and deductible. Postcodes map to premium regions with the official BAG table.
Not included: cantonal premium subsidies, discounts from the second child, and cross-border (EU) tariffs. The decade chart uses the lowest or highest deductible — whichever is closer to yours — so years compare like with like. The premium increase for every canton is in all 26 cantons, 2027; the long view is in the Expat Health Insurance Index; switching itself is explained in the switching guide.