
Health insurance premium calculator — compare every insurer by postcode.
This calculator is priminfo in English: it compares every insurer's officially approved 2027 basic premium for your postcode, age, deductible and model, with the change since 2026 and each insurer's history since 2016. Basic benefits are identical, so the ranking is a pure price ranking. To switch for 1 January, switch before 30 November.
2027 premiums are out: the Federal Office of Public Health published them on 29 September 2026. Every insurer below shows your own 2026 → 2027 change. To switch for 1 January, your cancellation must reach your insurer by 30 November. What changed in 2027
Median insurer · 2027
515.20CHF a month
Pick your insurer to see your own premium and its change since 2026.
Cheapest for this profile
471.10CHF a month
Sumiswalder
Cheapest vs most expensive
1'327CHF a year
for identical basic cover — benefits are the same by law
Every insurer, ranked · 2027
monthly premium · change since 2026
- 1 SumiswalderBASE 471.10 +5.1%
- 2 SLKKBASE 474.40 +5.8%
- 3 SanitasBASE 479.90 +4.9%
- 4 EGKBASE 488.40 +4.6%
- 5 WädenswilBASE 489.70 +5.0%
- 6 SympanyBASE 489.90 +6.9%
- 7 AtupriBASE 490.20 +4.2%
- 8 AssuraBASE 491.00 +5.3%
- 9 ConcordiaBASE 495.00 +3.1%
- 10 Mutuel (Groupe Mutuel)BASE 496.30 +4.3%
- 11 KPTBASE 498.10 +3.1%
- 12 ÖKKBASE 505.70 +9.5%
- 13 HelsanaBASE 509.40 +6.4%
- 14 Avenir (Groupe Mutuel)BASE 515.20 +9.2%
- 15 rhenusanaBASE 515.90 +9.0%
- 16 AquilanaBASE 516.60 +5.0%
- 17 Luzerner HinterlandBASE 516.80 +14.0%
- 18 SWICABASE 524.40 +7.4%
- 19 AgrisanoBASE 525.40 +8.1%
- 20 SteffisburgBASE 529.50 +2.5%
- 21 Einsiedler KrankenkasseBASE 534.20 +2.5%
- 22 sana24BASE 536.00 +3.2%
- 23 Philos (Groupe Mutuel)BASE 540.80 +2.7%
- 24 CSSBASE 548.40 +12.8%
- 25 vita surselvaBASE 551.80 +2.8%
- 26 VisanaBASE 566.00 +4.4%
- 27 GalenosBASE 581.70 +4.5%
Zürich city (premium region 1), adult 26+, CHF 2’500 deductible, standard model, accident excluded. Each insurer's cheapest approved tariff for this profile.
The decade behind the price
your insurer market median cheapest that year
History at the CHF 2’500 deductible, so every year compares like with like.
The price is the easy part. Four things it cannot see.
Your supplementary contract
Basic cover moves freely — every insurer must accept you. Supplementary doesn't: a new insurer can ask health questions and say no. Cancel it first and it may be gone for good.
Whether the model fits your life
The cheapest rows are often HMO or telmed. They work well — until you see a specialist without the referral and the claim comes back refused.
Your deductible break-even
CHF 2’500 saves premium. With regular treatment it can cost you more than it saves. The break-even is arithmetic, and it depends on your year, not an average one.
Coverage that pays vs coverage that fights
Premiums are public; claim behaviour isn't. Two insurers at the same price can treat the same invoice very differently. That part we see every week.
Bring your premium letter. Leave with it in writing.
In 45 minutes we read your 2027 premium letter against your supplementary contract, your model and your deductible — then send your free personal report within 3 working days. Sometimes it says keep what you have.
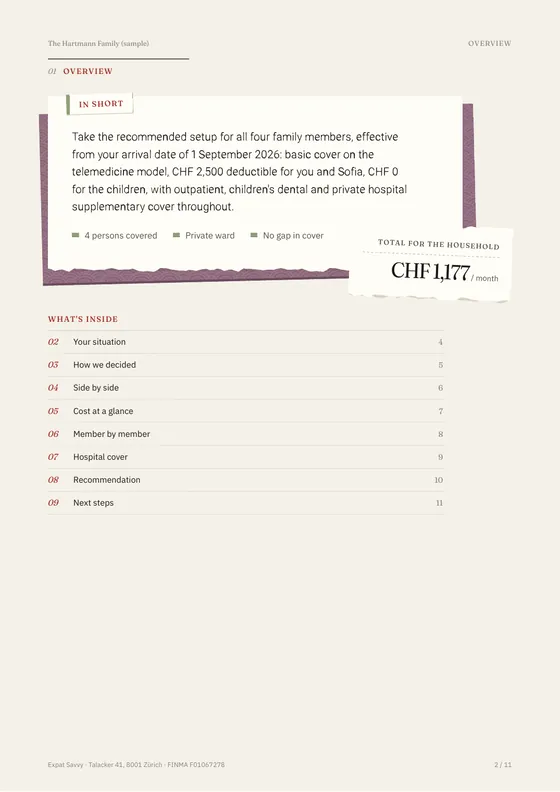
- 01Your situation
- Canton, family, work, the cover you hold today.
- 02How we decided
- The reasoning in writing — why each option won or lost.
- 03Side by side
- The real alternatives, including the one we advised against.
- 04Cost at a glance
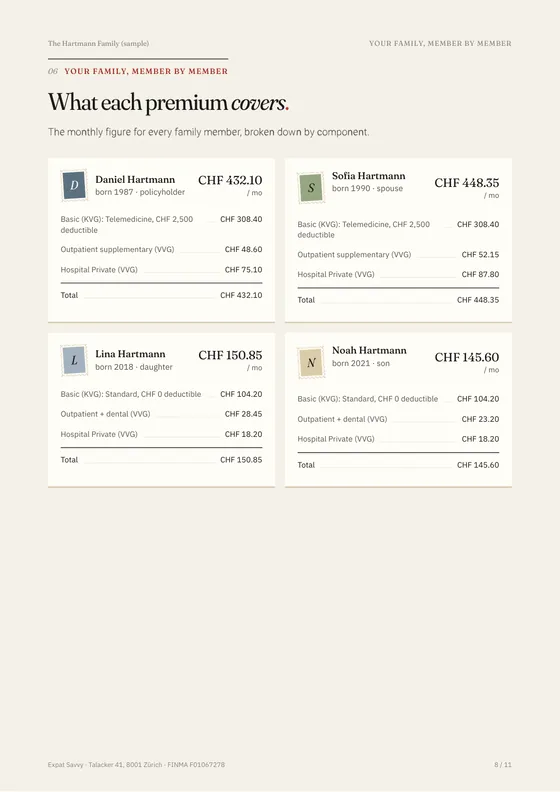
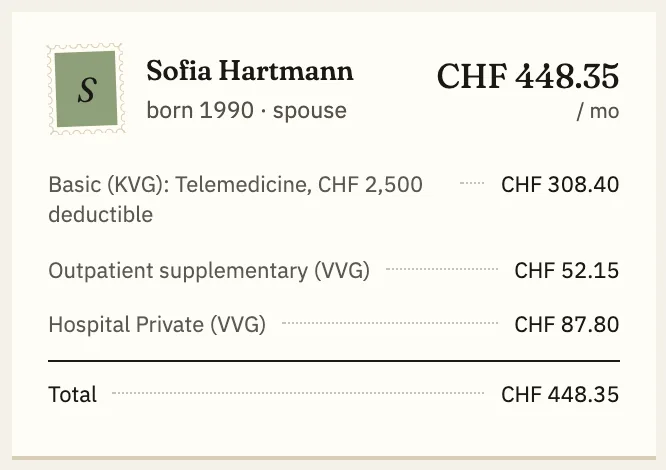
- What every person pays, to the franc.
- 05Recommendation
- What to do, in order — and what not to buy.
Open it full-screen · Download the PDF · What's inside
Method and source
Every figure is an officially approved list premium from the Federal Office of Public Health's open dataset "Krankenversicherungsprämien", tariff years 2016–2027. For each insurer we show its cheapest approved tariff for the model you pick, in your premium region, age group and deductible. Postcodes map to premium regions with the official BAG table.
Not included: cantonal premium subsidies, discounts from the second child, and cross-border (EU) tariffs. The decade chart uses the lowest or highest deductible — whichever is closer to yours — so years compare like with like. The premium increase for every canton is in all 26 cantons, 2027; the long view is in the Expat Health Insurance Index; switching itself is explained in the switching guide.