 Video, 3 min 15 s
Private health insurance in Switzerland: is it worth it?
Is private health insurance worth it in Switzerland?
Your first Swiss insurance review with Expat Savvy is 45 minutes, free, in English, by video call. We read your contracts with you on screen and tell you to stay, switch or restructure. No contracts are signed in the first call.
The full guide
Your first Swiss insurance review, step by stepWe read them with you on screen and tell you whether to stay, switch or restructure.
Book your first Swiss insurance reviewWhat actually happens in a free Swiss insurance review, in English? The short answer: 45 minutes, free, by video call, with Robert, Nicole or Benjamin. We read your contracts with you, and tell you to stay, switch or restructure.
The review is for people who want to know exactly how they are insured, today and for the years ahead: supplementary cover, pension planning, the third pillar. Health insurance is the one investment we all hope never pays out. That is exactly why it's worth knowing what you really have.
When you book, we email you a short intake form. Filling it in is optional, but it helps us prepare before we meet. Before the call, gather five things, about 10 minutes of admin. Your basic policy schedule. Any supplementary schedules. Your latest payslip, for the accident and pension lines. Insurer letters from the last 12 months that confused you. And, if you are self-employed, your AHV confirmation.
The first five minutes are about you. Just arrived, settled, or leaving? Who is in your household? How do you work? Any health history a questionnaire would ask about, briefly. We don't sell anything here. Five minutes of listening saves 20 minutes of wrong calculations.
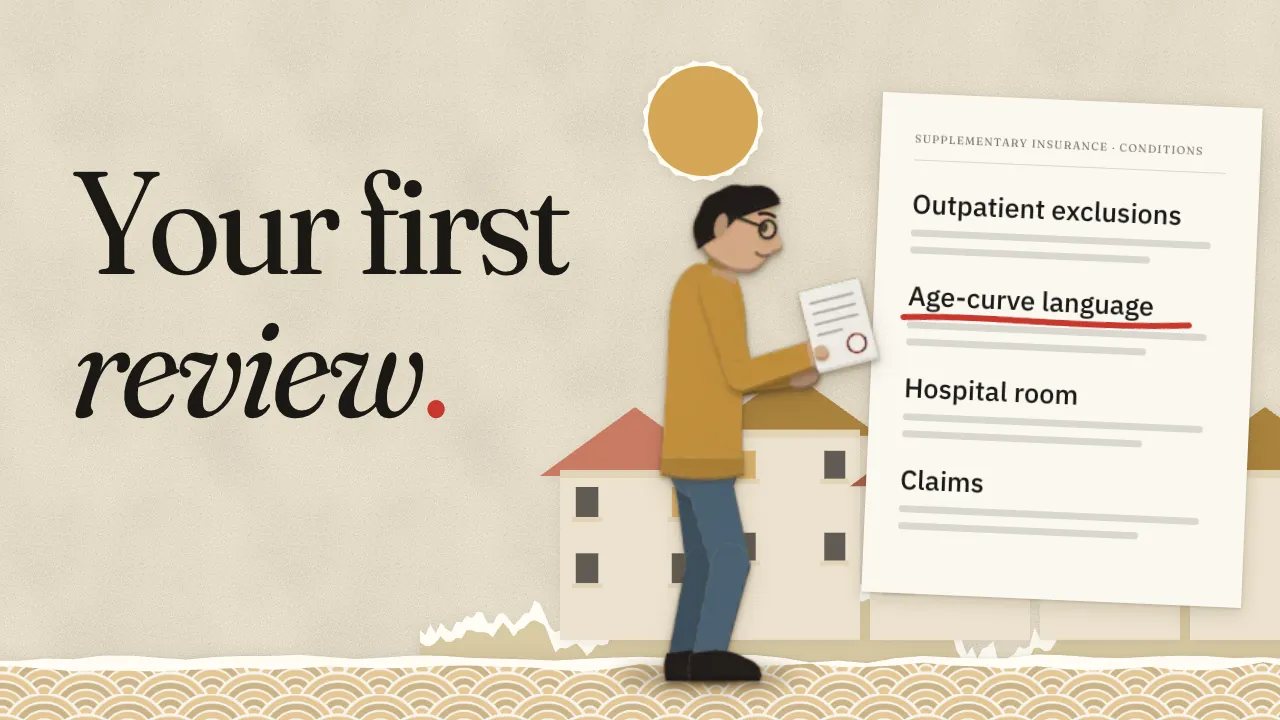
The middle 30 minutes are the work. On a shared screen, we read your contracts with you and mark the clauses worth reading: outpatient exclusions, the age-curve wording, the hospital-room definition, and the footnotes that decide whether a claim is paid or fought. Then the calculations. Your deductible at your age and canton, at the typical adult turning points: CHF 300, 1,500 and 2,500. Your model: standard, family doctor, HMO or Telmed. Gaps and overlaps in accident cover, supplementary and pension. And where the four traps apply to you.
The last 10 minutes are our recommendation. Stay: what you have already fits. Switch: a specific change, with the date and the steps. Or restructure: the setup is wrong, even if the products are not. We say stay more often than switch.
Within three working days, a written summary follows: sequenced, dated, deadlines marked. It shows what you have today, what each contract covers and leaves out, the numbers we worked out, and what to do in which order. We don't issue contracts in the first call. If you act, we do the paperwork; if not, there is no sales follow-up.
When should you not book us? If you've been here for years with one insurer, no supplementary, no chronic condition, and you're under 40: our premium calculator on expat-savvy.ch, or priminfo.ch, compares basic insurance for you in a few minutes. For price shopping, a comparison portal is fine. And to just sign a form, your insurer's portal is faster.
If you'd like someone to read your own contracts with you, book your first Swiss insurance review. It's free, 45 minutes, in English, with Robert or Nicole. The link is in the description.
Video, 3 min 15 s Is private health insurance worth it in Switzerland?
 Video, 3 min 23 s
Basic health insurance in Switzerland is mandatory and gives the same benefits at every insurer, by law.
 Video, 2 min 52 s
The cheapest Swiss health insurer gives exactly the same basic benefits as the most expensive one, by law.