 Video, 3 min 57 s
What happens in a free Swiss insurance review, in English
Your first Swiss insurance review with Expat Savvy is 45 minutes, free, in English, by video call.
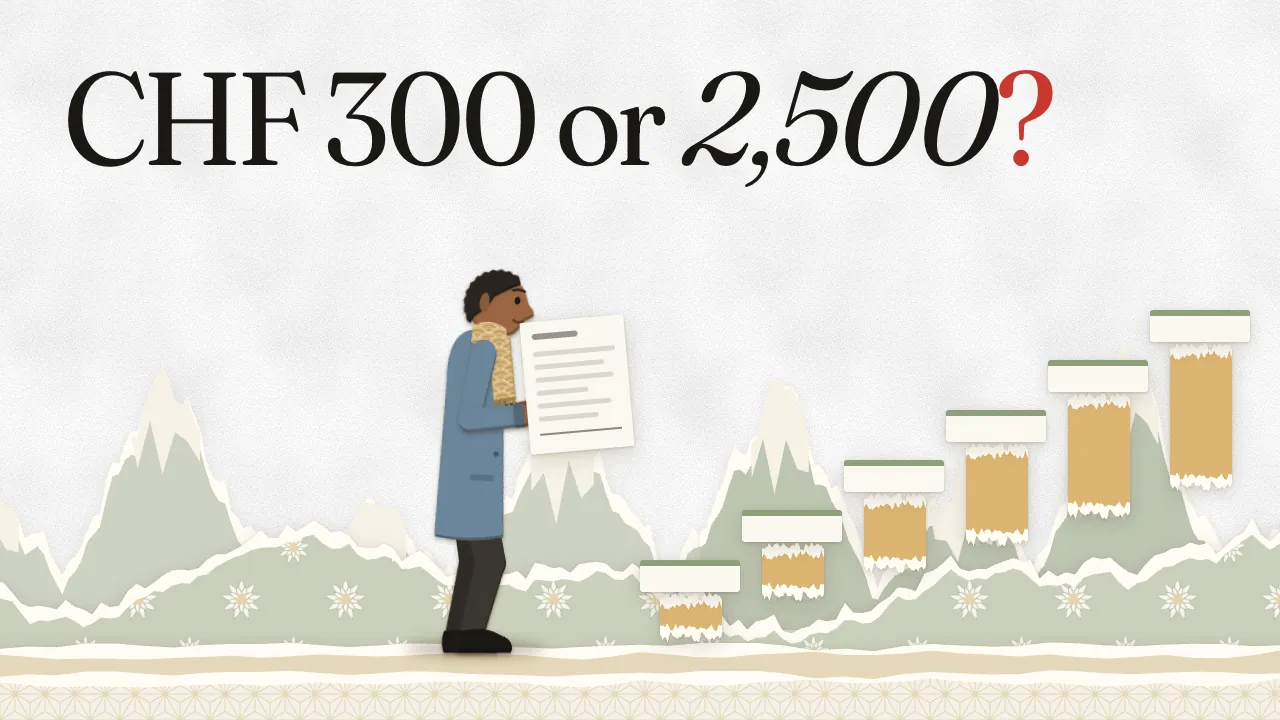
Which deductible (franchise) should you choose for Swiss health insurance? You pay the deductible first, then 10% of costs up to CHF 700 a year. If you rarely see a doctor, a higher deductible usually wins; if you have regular costs, it rarely does.
The full guide
How to choose your deductibleWe read them with you on screen and tell you whether to stay, switch or restructure.
Book your first Swiss insurance reviewWhich deductible should you choose for Swiss health insurance: CHF 300, or 2,500? And why did you get a bill after seeing a doctor?
The short answer: it depends on your actual yearly medical costs, not on your appetite for risk. Under CHF 1,000 a year, 2,500 usually wins. Over 3,000, usually 300.
Here is where the bill comes from. Your bills for the year add up to CHF 2,000. First, you pay your deductible: 300. Above it, 10%: 170. Your insurer pays the rest. You pay 470.
The 10% stops at CHF 700 a year. There are six deductibles, from 300 to 2,500. A higher one lowers your premium, but the law caps the discount: at most CHF 1,540 a year.
A trap we catch every week: the highest deductible, taken for its discount. In our worked example, an adult in Bern spends about CHF 4,800 a year on physiotherapy and medication. On 2,500, even after the largest discount, that year costs CHF 1,190. On 300, CHF 750: at least CHF 440 less.
Children are different. Three or more children at the same insurer, on the default deductible of zero, pay at most CHF 1,000 a year together. Split them across insurers, and that cap is gone. Raise each child's deductible to 600, and it rises to about 1,900.
One exception: pregnancy. Check-ups and the birth come with no deductible and no 10%. And from week 13 until eight weeks after the birth, everything medically necessary is covered in full.
So add up last year's medical bills, and pick the level that fits. You can change it every year: tell your insurer by 30 November, for 1 January.
If you'd like someone to read your own contracts with you, book your first Swiss insurance review. It's free, 45 minutes, in English, with Robert or Nicole. The link is in the description.
Video, 3 min 57 s Your first Swiss insurance review with Expat Savvy is 45 minutes, free, in English, by video call.
 Video, 3 min 15 s
Is private health insurance worth it in Switzerland?
 Video, 3 min 23 s
Basic health insurance in Switzerland is mandatory and gives the same benefits at every insurer, by law.